
Why a great backtest fails live: the +201 % Bitcoin example in short
November 5, 2026 · 0:49
A backtest can always find a perfect past. The short version of our +201 % Bitcoin test, and the one check that tells luck from an edge.
Home / Videos / Backtest overfitting on Bitcoin: a +201 % strategy on new data
Published on October 28, 2026 · Length 1:06 · Last updated: November 13, 2026
Every trading channel can show you a backtest with a great result. In this video we went looking for one ourselves, found +201 %, and then did the one thing most backtests skip: we ran the exact same setting on the time that came after.
The test was simple on purpose. We took a moving average crossover on the Bitcoin perpetual with 30 minute candles. The rule is always in the market: long when the fast average is above the slow one, short when it is below. Fees of 0.045 % per side were included on every trade (see maker and taker fees). Then we tried 1,474 combinations of the two averages on the years 2021 to 2024.
The winner was an EMA 7/180 pair. On those four years it made +201 %. That looks like a strategy you could sell in a course. Bitcoin itself made +189 % over the same period, so the winner even beat simply holding.
Then we moved the clock forward. From January 2025 to October 2026 the very same setting lost 74 %. Bitcoin fell about 14 % in that time, so the strategy did far worse than the market. It was not one unlucky setting either: of the 100 best settings from 2021 to 2024, not a single one made money in the new period.
This is what overfitting looks like. When you try enough settings, one of them will fit the past almost perfectly, because it has learned the noise of those exact years. The search does not find an edge, it finds the best story about history. The more combinations you test, the more impressive the winner looks and the less it means.
The only fair check is data the search never saw. That is how M Alpha Core works: the scan looks for the best settings of its built-in strategy for your market on the first 65 % of a year and keeps the last 35 % locked away. A setting is only recommended if it also passes on those unseen months, and if it fails a quality gate it is dropped. You can read more about this in backtesting on data the search never saw.
There is a shorter version of this topic as well, focused on the one lesson to take away. The page here is the full study with the method and all numbers.
More on this topic: Backtest on data the search never saw.
The short version of this test focuses on one question: how to spot a backtest that will not survive the next year. Watch the short version: Why a great backtest fails live: the +201 % Bitcoin example in short
November 5, 2026 · 0:49
A backtest can always find a perfect past. The short version of our +201 % Bitcoin test, and the one check that tells luck from an edge.
October 26, 2026 · 0:32
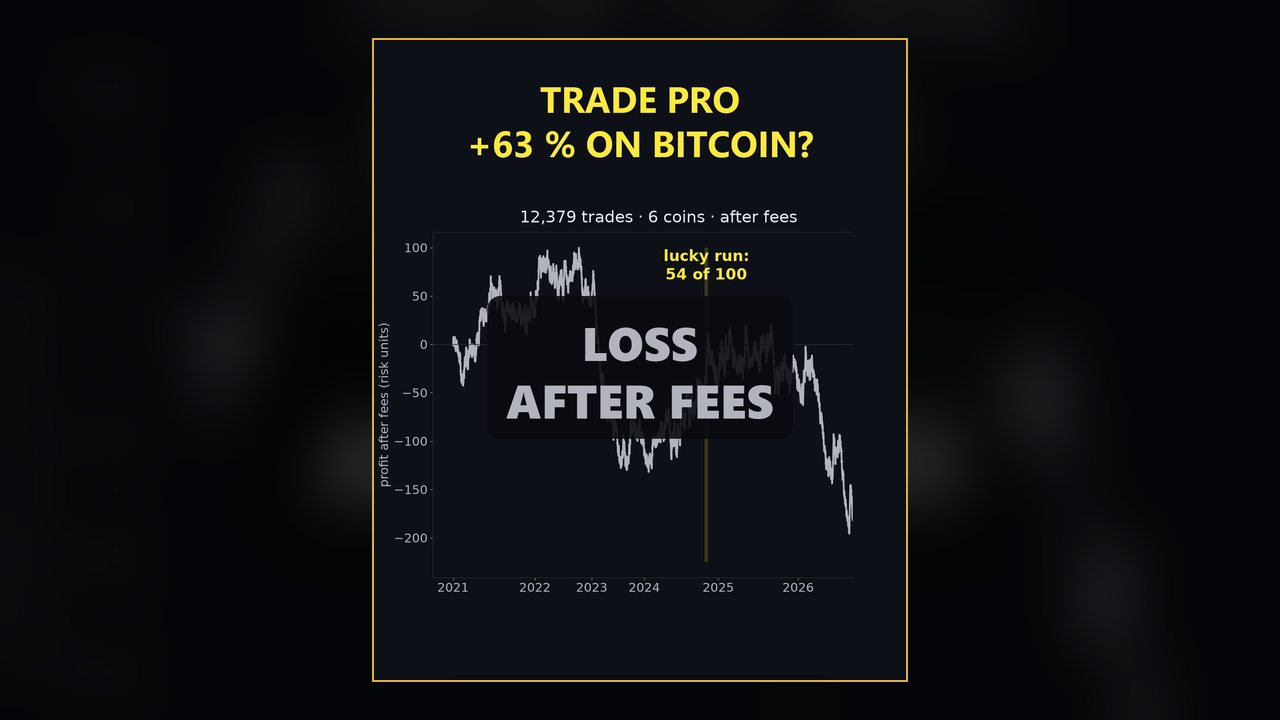
Heikin Ashi with Parabolic SAR and the 200 EMA: +63 % on Bitcoin in the original, a loss after fees across 12,379 trades in our test.
October 27, 2026 · 0:59
Trade Pro's 1 minute scalping: a tiny profit before fees on 197,140 trades, but fees ate about 80 % of the risk. Profit factor 0.30.
October 27, 2026 · 0:57
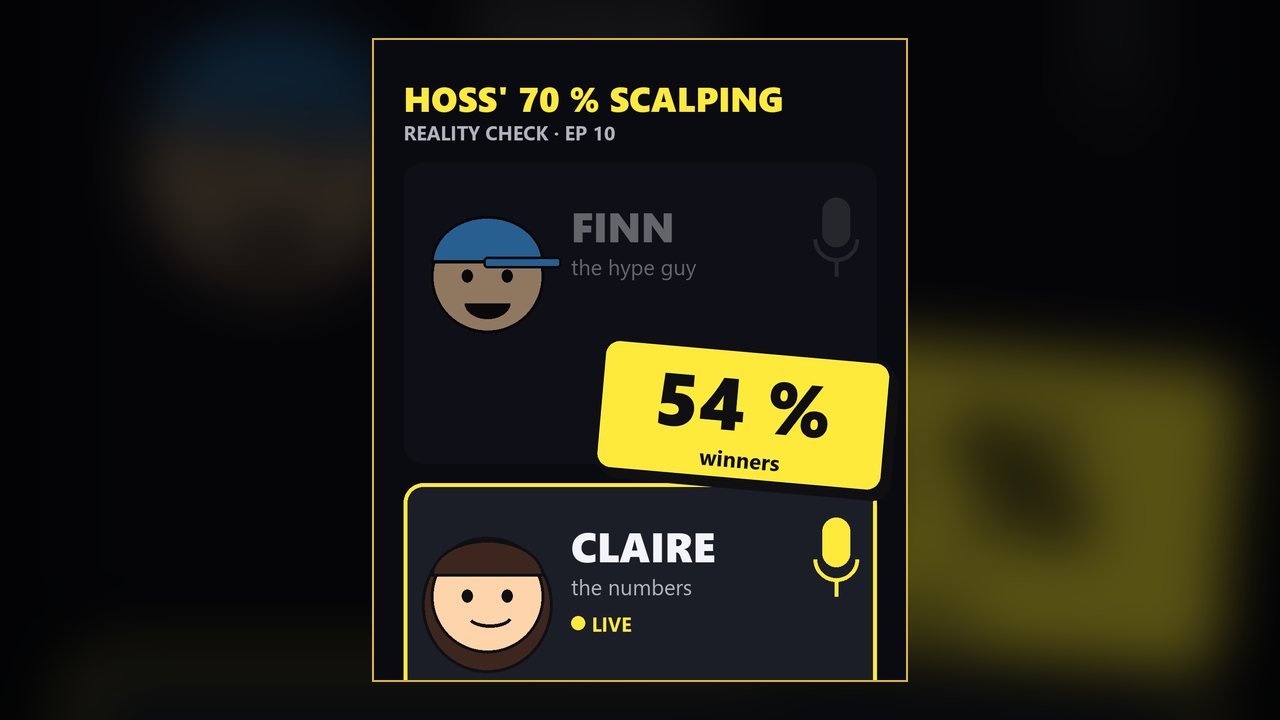
Hoss' 1 minute scalping with about 70 % winners: 67,117 trades on three coins, 54 % winners, and after fees every coin lost money.
All figures come from backtests on past market data. No result is a promise of future profit. Trading, especially with leverage, involves high risk. M Alpha Core is a software tool, not investment advice.