
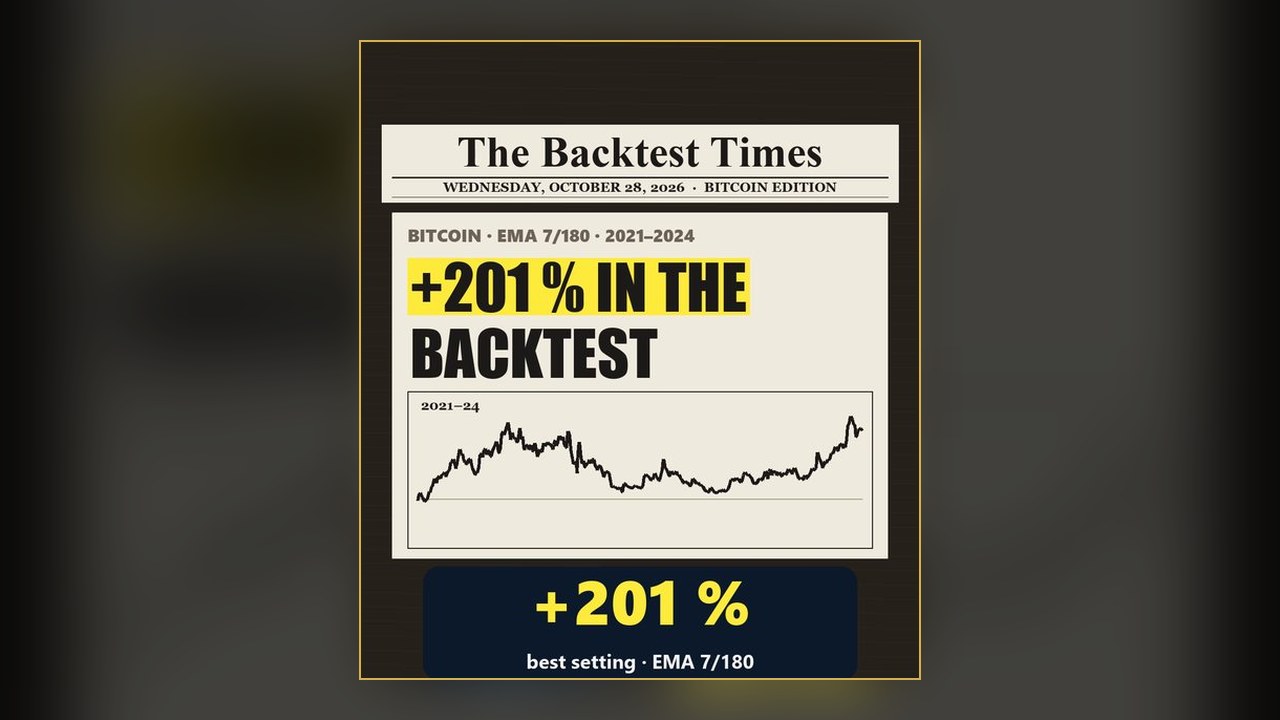
Backtest overfitting on Bitcoin: a +201 % strategy on new data
October 28, 2026 · 1:06
1,474 moving average settings on Bitcoin, 2021 to 2024: the best made +201 %. The same setting lost 74 % on the next 22 months. The full study.
Home / Videos / Why a great backtest fails live: the +201 % Bitcoin example in short
Published on November 5, 2026 · Length 0:49 · Last updated: November 13, 2026
This short video asks a question every trader should ask before trusting a backtest: would the result still hold on the next year?
The example is our own. We tried 1,474 settings of a moving average strategy on Bitcoin from 2021 to 2024. The best one made +201 %. Then we ran the exact same setting on 2025 and 2026. It lost 74 %. And of the best 100 settings, not a single one made money in the new period.
Why does this happen? A search over many settings will always find one that fits the past well. That does not mean it found something real. Markets change, and a setting tuned to old price swings often just memorised them. This is called overfitting, and it is the most common reason a strategy that looked perfect on paper fails with real money.
So how do you tell an edge from luck? Three simple checks help. First, ask how many settings were tried. The more combinations, the more likely the best one is luck. Second, ask whether the result was checked on a period the search never touched. Third, look at all trades, not only the final percentage: how many trades there were, how big the average loss was, and how deep the worst stretch went.
The second check is the one that matters most, and it is built into M Alpha Core. The scan searches the best settings of its built-in strategy for your market on the first 65 % of a year. The last 35 % stay hidden until the end. Only settings that also pass on those unseen months are recommended. Our guide to out of sample testing explains the idea step by step.
The video ends on a simple rule: measure twice, trade once. A good backtest is a start. A good result on data the search never saw is the real test.
More on this topic: Out of sample testing explained.
The full study with the exact rule, fees, time frame and the comparison with simply holding Bitcoin is in the longer video. Watch the full study: Backtest overfitting on Bitcoin: a +201 % strategy on new data
October 28, 2026 · 1:06
1,474 moving average settings on Bitcoin, 2021 to 2024: the best made +201 %. The same setting lost 74 % on the next 22 months. The full study.
November 5, 2026 · 0:48
One week after steady lads, LUNA was worth almost nothing. Most traders were asleep or hoping. Why two early warnings matter more than a calm quote.
November 4, 2026 · 0:42
Four days after assets are fine, about $8 billion of FTX customer money was gone. Why your bot should leave money and keys with you.
November 3, 2026 · 1:46
A full scan on SUI with 35 % of the data locked away: 97 trades, profit factor 4.13 searched and 5.47 on unseen months.
All figures come from backtests on past market data. No result is a promise of future profit. Trading, especially with leverage, involves high risk. M Alpha Core is a software tool, not investment advice.